Shirley Mueller’s team handles VA construction loans in Tennessee. One team works with you from pre-approval through move-in.
A Tennessee VA construction loan lets an eligible Veteran finance the lot, the construction and the permanent mortgage for a new primary residence, with $0 down on loans up to $1 million. My team works with Veterans building in Nashville, Knoxville, Chattanooga, Murfreesboro, Clarksville and rural Tennessee communities.
Why Veterans Choose a VA Construction Loan in Tennessee
Building lets you choose the lot and the floor plan instead of taking whatever is for sale. The main benefits:
- Zero down payment: Borrow up to $1 million with nothing down. Above $1 million, the maximum is $2 million and 5% down is required.
- No monthly PMI: VA loans don't require private mortgage insurance.
- One-time close financing: One closing covers the lot, the construction and your permanent mortgage.
- Fixed-rate terms: 15- or 30-year fixed only. Adjustable-rate mortgages aren't offered on VA construction loans.
- No payments during construction: You won't owe a mortgage payment until the home is finished. The builder pays the interest reserve and the construction management fee, both built into the loan amount.
- Finance land and construction: Buy a lot and build on it, or build on land you already own, all with one loan.
Build a Home with $0 Down in Tennessee
Tennessee has no state income tax on wages, which leaves more of your monthly income available for the residual income review that comes first in VA underwriting. Combined with $0 down on loans up to $1 million, that makes building a home in Tennessee within reach for many Veteran families.
VA Construction Loans We Offer in Tennessee
Each option below uses the same single-closing VA loan. What changes is whether you're buying the lot or already own it.
VA construction loan on land you already own in Tennessee
Own residential land? You may be able to use your equity. No structural work can begin before your loan closes, though site clearing is usually allowed. Building on land you own.
VA construction-to-permanent loan in Tennessee
Your builder is paid in draws during the 12-month build, and when the home is finished the same loan becomes your 15- or 30-year fixed VA mortgage. Construction-to-permanent details.
VA one-time close construction loan in Tennessee
A VA one-time close (OTC) construction loan in Tennessee combines construction financing and permanent financing into a single loan with one closing. One-time close details.
Who Is Eligible for a VA Construction Loan in Tennessee?
VA construction loans are for eligible Veterans, active-duty service members, qualifying National Guard and Reserve members, and certain surviving spouses. The Department of Veterans Affairs sets the basic eligibility requirements, and the lender adds its own construction guidelines.
If you're thinking about a VA new construction loan in Tennessee, my team will review your eligibility and explain your options before you commit to a builder or a lot.
You may qualify if you:
- Are an eligible Veteran, active-duty service member or qualifying surviving spouse
- Have a valid VA Certificate of Eligibility (COE)
- Will live in the home as your primary residence
- Meet credit and income guidelines. VA construction loans start at a 620 minimum credit score, and larger loan amounts may need a higher score.
- Can show enough income and residual income to repay the loan, with an Approve/Eligible finding from automated underwriting (manual underwriting isn't available for construction loans)
- Choose a licensed builder approved by the lender before closing who carries adequate general liability and workers' compensation coverage
- Plan a home that meets VA Minimum Property Requirements
- Are building on an eligible residential property in Tennessee. Working farms and ranches with active agricultural operations aren't eligible (see the West Tennessee section below).
Not sure whether you qualify? Applying is a soft credit pull. If you qualify, my team sends a pre-approval letter and a full itemized estimate. If not yet, you'll get a plan to get there.
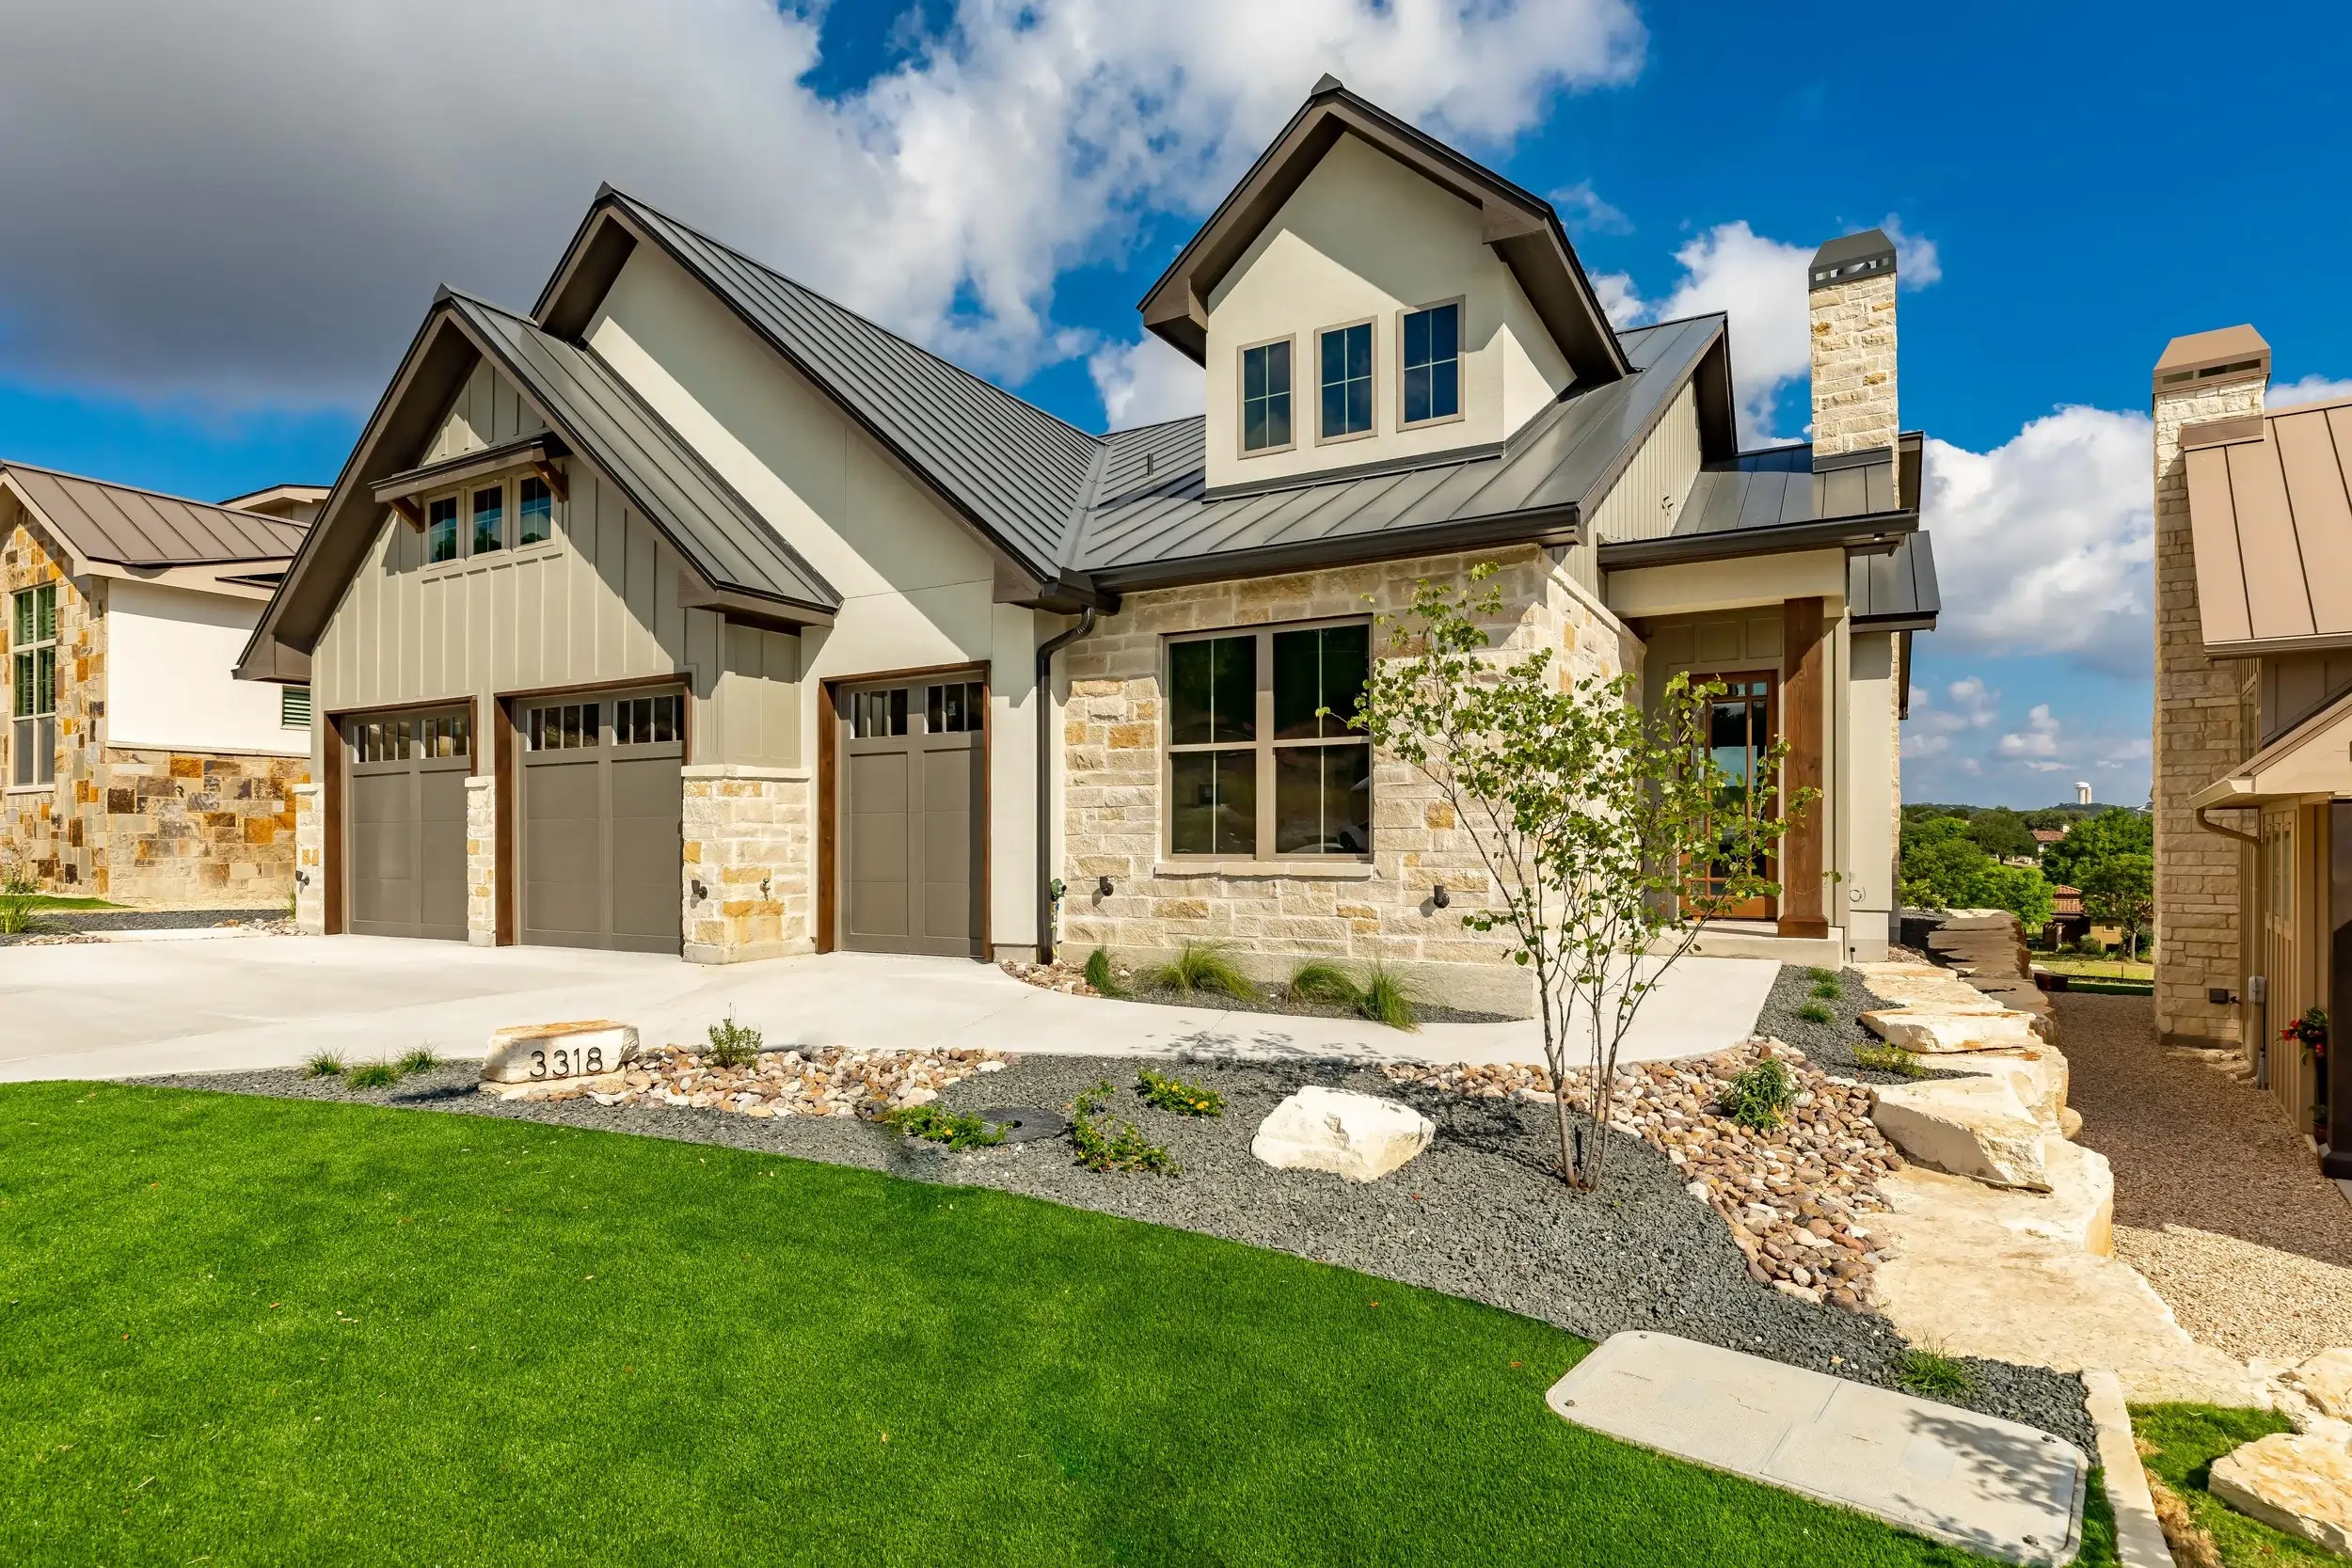
Tennessee VA Construction Loan Requirements
- VA Certificate of Eligibility (COE): Confirms your eligibility for VA home loan benefits.
- Occupancy requirement: The home must be your primary residence after construction. VA construction loans can't be used for vacation or investment properties.
- Credit and income: We review your credit history and stable income. Construction loans need at least two qualifying credit scores.
- Residual income and DTI: Residual income is reviewed first. A higher debt-to-income ratio is often fine when residual income is strong.
- Approved builder: A qualified builder approved by the lender before closing, typically carrying at least $500,000 per occurrence / $1,000,000 aggregate in general liability coverage plus active workers' compensation coverage or an approved exemption.
- Construction contract: A signed, fixed-price contract covering the scope, timeline and costs. Cost-plus contracts aren't eligible.
- Licensed Tennessee builder: Your contractor must meet state and local licensing requirements (see below).
- Property appraisal: The home's projected value must support the loan amount.
- Loan amount: A minimum loan amount of $100,000 and a $2 million maximum. $0 down up to $1 million, and 5% down on loans over $1 million.
- Build time: A 12-month construction period.
Veteran Property Tax Exemption in Tennessee
Tennessee offers property tax relief that can help qualifying disabled Veterans and certain surviving spouses. VA loan benefits and property tax exemptions are separate programs, but eligible homeowners can use both, which lowers the cost of owning the home once it's built.
The state's Property Tax Relief Program is run through each county trustee. For disabled Veterans, it's available to homeowners with a service-connected permanent and total disability as determined by the VA, as well as certain specific service-connected disabilities (such as paraplegia, loss or loss of use of two or more limbs, or legal blindness) and 100% disabled former prisoners of war.
What to know:
- Relief is calculated on up to $175,000 of your home's market value
- The home must be your primary residence, and you must own it
- Surviving spouses have a separate relief program with its own requirements
- Applications go through your county trustee's office
- A newly built home qualifies once it's assessed and you're living in it
Property tax procedures differ by county, so confirm the current requirements before you apply. In Davidson, Knox, Hamilton, Rutherford, Montgomery or any other county, the county trustee's office can explain the programs and filing deadlines. The Tennessee Department of Veterans Services' disabled Veteran tax relief page is a good place to start.
VA Funding Fee and Closing Costs for VA Construction Loans
Even with no down payment, building has costs. Plan for these:
- VA funding fee: A one-time fee based on your down payment and whether you've used your VA benefit before. It can be financed into the loan, and Veterans who receive VA disability compensation don't pay it.
- Appraisal fee: The VA appraisal values the proposed home from the approved plans and specifications. Inspections are also done during construction.
- Credit report and underwriting: Fees for reviewing your credit, verifying documents and underwriting the loan.
- Title and settlement services: Title search, title insurance and closing coordination to make sure ownership is clear.
- Recording and government fees: Charged by the county to record your mortgage and property documents.
- Homeowners insurance: You'll need coverage in place for the finished home.
- Prepaid expenses: Prepaid property taxes, insurance premiums and initial escrow deposits.
Closing costs depend on the loan amount and location. My team gives you a full itemized estimate early, so there are no surprises at closing. See our guide to VA construction loan closing costs.
Building a Home Across Tennessee: What Local Buyers Should Know
Building conditions change a lot between Memphis and the Smoky Mountains. Here's what to expect in each part of the state.
Middle Tennessee
Middle Tennessee, home to Nashville, Franklin, Murfreesboro, Hendersonville and Clarksville, continues to see strong residential growth. These areas have plenty of jobs and amenities, but high demand for land and builders can push up construction costs and booking times, so plan early. Clarksville sits right next to Fort Campbell, so it has a large military community.
East Tennessee
Knoxville, Johnson City and Sevierville attract buyers looking for mountain views and larger lots. Mountain properties often need extra site preparation, grading, retaining walls and specialized foundations. Many rural homes rely on private wells and septic systems, so soil testing is an important part of planning.
If you're looking at a lot in a cabin or chalet community near Sevierville or Gatlinburg, check how the development is legally set up. Some are structured as site condominiums, and under my team's current construction guidelines, site-condo lots in Tennessee aren't eligible for this VA construction program. Confirm the legal structure with my team before you sign a contract.
West Tennessee
The Memphis and Jackson areas offer a mix of suburban neighborhoods and rural farmland, often at lower lot prices. That makes West Tennessee attractive for Veterans who want more space while staying close to major highways and jobs. NSA Mid-South in Millington is nearby for those still serving.
If you're looking at farmland, keep in mind that a property with an active working farm or ranch operation isn't an eligible property type, even if the acreage would otherwise meet VA property standards. A large rural residential lot is usually fine. A working farm with an ongoing agricultural operation isn't. Confirm eligibility with my team before you make an offer.
Before construction begins, keep these local factors in mind:
- Permit requirements vary by county and city across Tennessee
- Utility availability differs between urban and rural properties
- Private wells and septic systems need their own approvals
- Sloped lots in East Tennessee can increase site preparation costs
- Properties near rivers may need a flood zone review
- Construction runs on a 12-month construction period, so plan your design and permits around it
In Tennessee, a contractor needs a license from the state Board for Licensing Contractors (part of the Department of Commerce & Insurance) for residential projects of $25,000 or more, which covers virtually any new home. Your builder's license is one of the first things my team checks during builder approval.
Partner With Us to Build Homes for Eligible Veterans
If you're a licensed Tennessee contractor and a client wants to use a VA construction loan, my team can start your builder approval early so it's finished well before closing. See builder requirements.
VA Construction Appraisal Considerations for Tennessee
Unlike a traditional home purchase, a VA construction appraisal is based on the projected completed value of your future home. The appraiser reviews your building plans, specifications, materials, location and comparable sales to decide whether the finished home's value supports the loan amount.
Every construction project is different, so careful planning and accurate documents matter. Delays often happen when plans change after the appraisal, so finalize your design before the appraisal is ordered.
Several local factors can affect your appraisal in Tennessee:
- Quality and completeness of the construction plans
- Comparable home sales in the surrounding market
- Lot location and accessibility
- Utility availability
- Site preparation requirements
- Mountain terrain or sloped lots
- Flood zone considerations
- Overall demand in your community
Homes in fast-growing markets like Nashville or Murfreesboro will have different comparable sales than homes in rural West Tennessee or the mountains of East Tennessee, and the appraiser accounts for those regional differences. My team works with you, your builder and the appraiser to get the right documents submitted the first time.
Check the VA Minimum Property Requirements checklist before you finalize your plans.
Why Work With Us
VA construction loan specialists
My team works on VA construction loans every day and coordinates each step with you and your builder, from pre-approval to the day the loan converts to your permanent mortgage.
20+ years of VA lending experience
The team is led by Shirley Mueller, Sr. VP of Veteran Lending at CrossCountry Mortgage, who has specialized in VA home loans for over 20 years.
Serving Veterans across Tennessee
My team handles your loan from application to move-in, whether you're building in Nashville, Knoxville, Chattanooga, Memphis, Clarksville, Murfreesboro or a small town.
Tennessee VA construction loan FAQs
Can I use a VA construction loan to build on rural land in Tennessee?
Yes. Eligible Veterans can use a VA construction loan to build on rural land in Tennessee as long as the property meets VA guidelines and local zoning, has legal access, and has utilities or an approved well and septic system where needed.
Does the U.S. Department of Veterans Affairs lend money directly for construction?
No. The VA doesn't lend the money. It guarantees part of a loan made by an approved private lender, which is what makes $0 down possible on loans up to $1 million.
What is a VA Certificate of Eligibility (COE), and how do I get one?
A Certificate of Eligibility (COE) confirms that you qualify for VA home loan benefits. My team can usually get it for you electronically, or you can request it directly from the VA.
Does my new home have to meet VA Minimum Property Requirements (MPRs)?
Yes. Every home financed with a VA construction loan has to meet VA Minimum Property Requirements (MPRs), which make sure the finished home is safe, structurally sound, sanitary and suitable for year-round living.
Can I choose any builder for my Tennessee VA construction loan?
You can choose your builder, but they have to hold the right Tennessee contractor license, pass our builder approval process before closing, carry the required insurance, and build under a fixed-price contract. Owner-builders and do-it-yourself work aren't allowed.
How do flood zones affect a VA construction loan in Tennessee?
If the property is in a FEMA Special Flood Hazard Area, flood insurance will be required. A site that floods regularly may not be eligible no matter how it's mapped. We review the flood designation as part of approval.
Can I include energy-efficient upgrades in my Tennessee VA construction loan?
In many cases, yes. Energy-efficient features such as high-efficiency HVAC, ENERGY STAR® windows, upgraded insulation and solar-ready construction can be part of the construction budget, as long as they're in the fixed-price contract and the appraisal supports the value.
How long is a Certificate of Eligibility (COE) valid?
A COE generally doesn't expire. We may pull an updated one if your entitlement has changed or you're using your VA benefit again.
Can I build a barndominium or modular home with a Tennessee VA construction loan?
Yes. Barndominiums and modular or hybrid-modular homes (single-unit, detached) are eligible, as long as they meet VA Minimum Property Requirements and local building codes.
Can I build on land with a working farm or ranch in Tennessee?
No. A property with an active agricultural operation, meaning a working farm or ranch, isn't an eligible property type, even in rural parts of West or Middle Tennessee. A large residential lot without a farming operation is usually fine. Check your property with my team before you make an offer.
What is the VA construction loan limit in Tennessee?
With full VA entitlement, there's no county loan limit. Your loan amount depends on your income, credit, entitlement and the appraised value, up to a $2 million maximum. You can borrow up to $1 million with $0 down. Loans over $1 million need 5% down. Borrowers with reduced entitlement may be subject to county loan limits.