VA Construction Loans for Veterans — Available in 48 States
VA Construction Loans in
Building a custom home is a major milestone, and eligible Veterans can make it more affordable with a VA construction loan in Arizona. Instead of financing construction and a permanent mortgage separately, a VA construction loan lets qualified military borrowers finance the construction of a new primary residence with as little as 0% down, competitive interest rates, and a single financing process.
Whether you’re planning to build in Phoenix, Tucson, Prescott, Flagstaff, Mesa, or anywhere across Arizona, our team helps Veterans understand every step from land acquisition to move-in day.

We are proudly serving those who served the nation.

When it comes to Arizona VA construction loans, experience matters. Shirley Mueller has spent 20+ years helping Veterans navigate the VA home loan benefit and has assisted over 3,000 military families in achieving homeownership through the VA loan program.
As Senior Vice President of Veteran Lending (NMLS ID: 336103), Shirley specializes exclusively in VA lending, including the unique requirements involved with financing new construction. Building a home is a different process than purchasing an existing one — from reviewing eligibility and Certificates of Eligibility (COE) to coordinating builder documentation and explaining construction timelines, Shirley helps Veterans understand what to expect before construction begins.
The Arizona builds I see run into trouble most often aren’t credit issues — they’re borrowers who fall in love with a lot before confirming it’s zoned for the construction type they want, or who sign a “cost-plus” contract without realizing VA construction loans only allow fixed-price contracts. Catching that before you’re under contract on land saves months.
Whether you’re an active-duty service member stationed at Luke Air Force Base, Davis-Monthan Air Force Base, Fort Huachuca, MCAS Yuma, or a retired Veteran looking to settle in Arizona, you’ll receive guidance based on current VA guidelines and construction requirements.
Arizona continues to attract Veterans because of its military communities, strong job market, year-round sunshine, and opportunities to build homes in growing cities and rural areas alike. A VA construction loan in Arizona gives eligible borrowers access to financing designed specifically for primary residences while minimizing upfront costs.

Qualified Veterans can often finance the construction of their new primary residence without a traditional down payment.

A VA One-Time Close loan combines construction financing and the permanent mortgage into a single loan.

VA-backed financing generally offers favorable interest rates compared to many conventional construction loan options.
Under current construction guidelines, the builder — not the borrower — covers interest-only payments during the build, so borrowers typically make no monthly payments while the home is under construction.
Current construction underwriting allows many qualified Veterans to become eligible even without perfect credit, provided applicable requirements are met.
Rather than buying an older home that needs renovation, you can build around your family’s needs, floor plan, and energy-efficient preferences.
An Arizona VA construction loan gives eligible Veterans and active-duty service members the opportunity to build a custom primary residence with 0% down, subject to VA eligibility and current lending guidelines.
Rather than settling for an existing home, you can build in Phoenix, Tucson, Mesa, Chandler, Gilbert, Flagstaff, Prescott, Yuma, or anywhere across Arizona.
Whether you’re purchasing a homesite or already own land, a VA One-Time Close construction loan can simplify financing by combining construction and permanent mortgage financing into one loan.
Explore our Arizona VA construction financing programs, created to help veterans build a home that supports their lifestyle, financial goals, and future.

own your Arizona lot? You may be able to use your land as part of your new construction financing while building your primary residence.
Finance construction and transition into your permanent mortgage through one streamlined financing solution designed for eligible Veterans.
Complete your construction financing and permanent mortgage with one closing, helping simplify the process while reducing duplicate closing costs.
A VA construction loan in Arizona is available to eligible military borrowers who meet the Department of Veterans Affairs’ service requirements and qualify for a Certificate of Eligibility (COE).
(VA.gov: VA home loan eligibility requirements) Meeting the service requirement is the first step, but borrowers must also satisfy current lender underwriting guidelines before financing can be approved.
Meet current credit, income, and residual income guidelines.

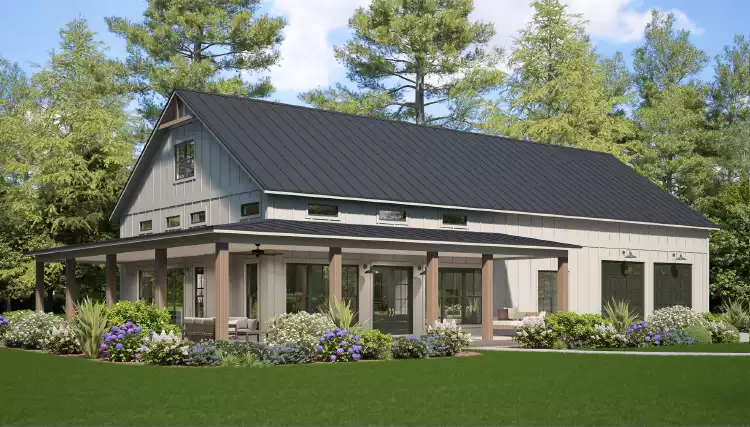
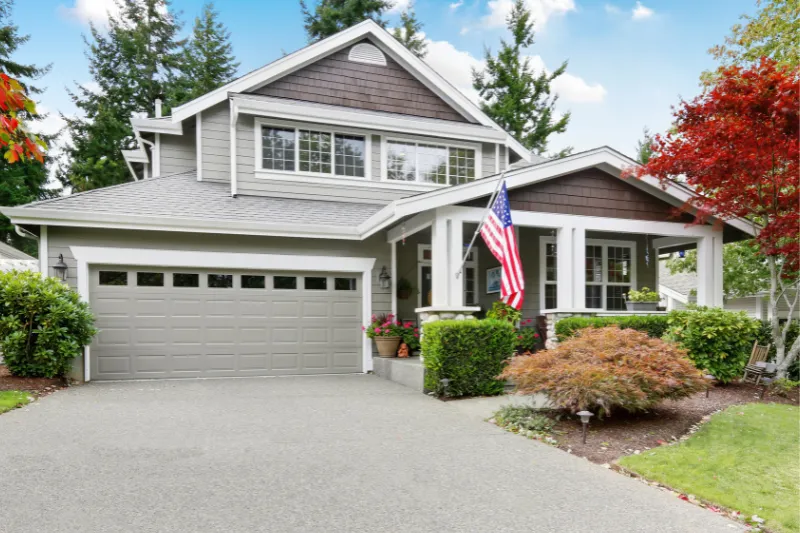
Under current construction guidelines, eligible property types in Arizona include:
Barndominiums.
A few property types are not eligible for VA construction financing: attached homes, agricultural properties with working farms or ranches, mixed-use properties, container homes, and any lot where permanent structural work (footers, foundation, slab) has already begun — VA construction loans only cover proposed, not already-underway, construction.
Obtain your Certificate of Eligibility (COE) and review your financial qualifications before beginning your home-building project.
Your lender reviews your income, credit profile, military eligibility, and preliminary construction plans to determine your financing options.
Choose a licensed Arizona builder and finalize your construction contract, home plans, specifications, and project budget.
The proposed home is appraised, documentation is reviewed, underwriting is completed, and your construction loan is prepared for closing.
After closing, construction funds are released through scheduled draws as work progresses according to the approved timeline.
Once construction is complete, the final inspection and occupancy requirements are satisfied, allowing you to move into your newly built Arizona home.

Arizona offers property tax relief for qualifying veterans with disabilities, and this benefit changed meaningfully in 2026.
Under Arizona House Bill 2792, effective February 12, 2026, veterans with a 100% VA service-connected disability rating may now qualify for a full property tax exemption on their primary residence — a significant expansion from the small, prorated exemption previously available at that tier.
Veterans with a disability rating below 100% may still qualify for a prorated exemption tied to their disability percentage, subject to income and property value limits set annually by the Arizona Department of Revenue. (Arizona Revised Statutes § 42-11111)
Because exemption amounts, income caps, and property value limits are administered at the county level and adjusted for inflation each year, confirm your current figures directly with your county assessor after your home is complete.
Veterans building in counties such as Maricopa, Pima, Yavapai, Pinal, Mohave, Yuma, or Coconino should contact their county assessor’s office for application deadlines and required documentation, including your VA disability rating letter.
When budgeting for a VA construction loan in Arizona, plan for both the VA funding fee and standard closing costs.
Most first-time users finance with a 2.15% funding fee when putting no money down; the fee can typically be rolled into the loan rather than paid upfront.
Veterans receiving VA disability compensation, and certain surviving spouses, are exempt from the funding fee entirely. (VA.gov: VA funding fee and closing costs)
In addition to the funding fee, borrowers should be prepared for:
With a VA One-Time Close construction loan in Arizona, construction financing and your permanent mortgage combine into a single closing, which helps reduce duplicate closing costs compared to separate construction and mortgage loans.

Building a home with an Arizona VA construction loan requires more than choosing a floor plan. Your project must comply with VA guidelines, Arizona building codes, local zoning laws, and county permitting requirements before construction can begin.
Each Arizona city and county has its own zoning regulations, permit process, and inspection requirements. Whether you’re building in Phoenix, Scottsdale, Mesa, Chandler, Gilbert, Tucson, or Prescott, verify that your land is properly zoned for residential construction before purchasing.
Arizona’s hot, dry climate makes energy-efficient construction a smart investment. Many Veterans choose high-performance insulation, energy-efficient windows, high-efficiency HVAC systems, reflective roofing, and drought-tolerant landscaping.
If you’re building in areas like Flagstaff, Sierra Vista, Payson, Kingman, or Yuma, review access to utilities, private wells, septic systems, easements, and flood zones. The completed home must also meet VA Minimum Property Requirements for safety and livability.
Your builder must meet Arizona licensing requirements, carry the required insurance, and provide applicable warranties. Although the VA no longer requires a Builder ID for most new construction loans, working with a builder familiar with VA construction requirements helps keep the process smooth.
If you’re a licensed Arizona builder interested in constructing homes for eligible Veterans, we’d love to connect. Builders must meet applicable Arizona licensing, insurance, and warranty requirements. While a VA Builder ID is no longer required for standard VA construction loans, compliance with current construction guidelines remains essential.
A VA construction appraisal determines the property’s estimated market value based on the proposed plans, specifications, and comparable new construction in the surrounding area. It’s an important part of loan approval, but it isn’t the same as a home inspection.
For newly constructed homes in Arizona, the appraisal is completed using the approved building plans before construction begins.
As construction progresses, inspections may be required before funds are released through scheduled draw requests.
The completed home must satisfy VA Minimum Property Requirements — safe, structurally sound, sanitary, and suitable for year-round occupancy, with adequate access, potable water, proper sewage disposal, and permanent heating.
As of mid-2026, VA reports the average appraisal nationwide takes approximately seven business days, though actual timelines vary by property location, appraiser availability, and market conditions.
(VA.gov: VA updates home loan appraisal requirements, June 2026)

Our experience with Arizona VA construction financing allows us to guide Veterans through the unique documentation and construction requirements involved with building a new home.
From reviewing your Certificate of Eligibility to coordinating with your builder and answering your questions throughout construction, we’re here to provide clear communication from start to finish.
Whether you’re building in Phoenix, Tucson, Flagstaff, Prescott, Yuma, Mesa, Gilbert, Chandler, Sierra Vista, or another Arizona community, we’re committed to helping you navigate the process with confidence.
Yes. Eligible Veterans can use an Arizona VA construction loan to build a custom primary residence. Depending on the loan program, you may also be able to finance the land purchase or build on land you already own. The home must be built by a qualified builder and meet VA and local building requirements.
Many eligible Veterans can qualify for 0% down financing, although final approval depends on available entitlement, the loan amount, and current lender guidelines.
Yes. Many Arizona VA construction loan programs allow you to build on land you already own, provided the property and construction project meet VA and lender requirements.
The VA does not set a minimum credit score, but individual lenders establish their own underwriting requirements. Credit score expectations may vary depending on the loan amount and overall financial profile.
Yes. A Certificate of Eligibility (COE) is required to verify your entitlement for a VA-backed home loan. Most participating lenders can help you obtain your COE during the application process.
No. As of March 31, 2025, the VA no longer requires a VA Builder Identification Number for standard VA-guaranteed new construction loans. However, builders must still comply with Arizona licensing requirements and provide the required warranties.
Yes, with conditions. A 2-4 unit property is eligible if you occupy one unit as your primary residence — the other units’ potential rental income can’t be counted toward qualifying. Arizona is also one of a small number of states where a detached site condo is eligible for VA construction financing, alongside Michigan and Utah.
In many cases, yes. Eligible borrowers may finance the VA funding fee into the total loan amount instead of paying it at closing. Veterans with qualifying service-connected disabilities and certain surviving spouses may be exempt from paying the funding fee.
Construction timelines vary based on the builder, home design, weather, and local permitting. Most construction periods are scheduled for several months, with funds released in stages as the project progresses.
Yes. A VA appraisal is typically completed using the proposed building plans and specifications to determine the home’s estimated market value. The completed home must also meet VA Minimum Property Requirements before occupancy.
Yes. Eligible active-duty service members stationed at installations such as Luke Air Force Base, Davis-Monthan Air Force Base, Fort Huachuca, or Marine Corps Air Station Yuma may qualify if they meet the VA’s service and eligibility requirements.
If you’re ready to build a home with a VA loan in Arizona, now is the perfect time to explore your options. Whether you’re purchasing land, already own a homesite, or are just beginning to research VA construction loans in Arizona, our team is ready to help you understand your eligibility, review your financing options, and guide you through every step of the construction process.
Contact us today to take the first step toward building your new Arizona home.