 ↑ Back to topics
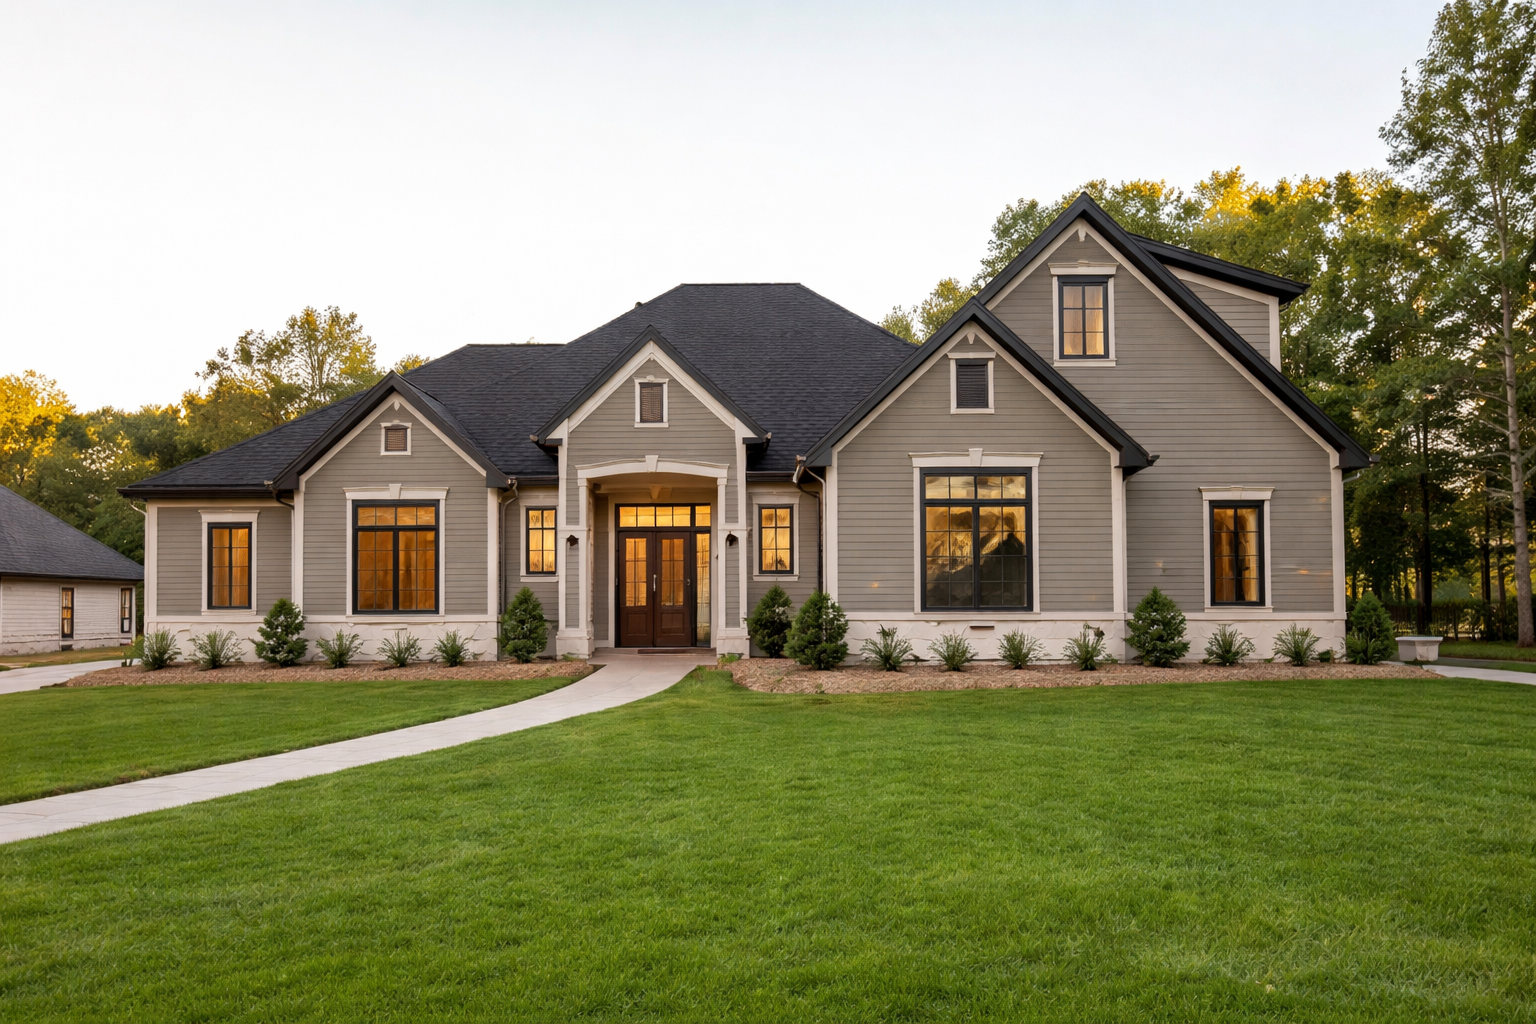
Real VA Construction Loan Project: Custom Texas Ranch Home Built with a One-Time Close VA Loan
This real VA construction loan project shows how a Veteran built a fully custom home in Texas using a VA One-Time Close Construction Loan, with the land purchase, construction and permanent financing in a single closing.
If you're a Veteran considering building instead of buying an existing home, this detailed breakdown covers the home design, floor plan highlights, loan structure, project timeline, and lessons learned, so you have a realistic picture of building custom with your VA loan benefit in Texas.
The VA construction-to-permanent loan — also called the One-Time Close (OTC) — is underused by eligible Veterans. It removes the need for multiple lenders, multiple closings and construction-phase payments, with $0 down on loans up to $1 million.
Why this matters: Many Veterans are told VA construction loans are too complex or unavailable. With a lender that offers this product, a fully custom 5,300 sq ft ranch home on acreage was financed through the Veteran's VA benefit at $0 down.
Project Snapshot
Loan & Build Details | |
|---|---|
| Loan Type | VA One-Time Close Construction Loan |
| Location | North Texas (withheld for privacy) |
| Home Size | ~5,300 sq ft |
| Bedrooms | 4 |
| Bathrooms | 3+ |
| Garage | 3-Car |
| Home Style | Custom Ranch — Brick & Stone |
| Lot Type | Acreage Homesite |
| Land Purchase | ~$150,000 |
| Construction Cost | ~$650,000+ |
| Total Loan Amount | ~$900,000+ |
| Down Payment | $0 |
What Makes This Project Notable
At over 5,300 square feet, this is a large custom build, and it was financed through the Veteran's VA benefit with no down payment. The VA One-Time Close Construction Loan combined the land purchase, construction costs, soft costs, and permanent financing into a single loan transaction closed once before a single shovel broke ground.
The builder selected was a Texas-based custom home specialist with direct experience in acreage builds — which mattered for the rural site work, local permitting and the lender's construction draw requirements. VA doesn't approve builders; the lender does, before closing, so choosing a builder who can pass that review is one of the most important decisions in the process.
The final loan amount exceeded $900,000 — demonstrating that the VA One-Time Close is not limited to modest builds. Larger VA construction loans are available too: $0 down on loans up to $1 million, and loans over $1 million (up to $2 million) need 5% down.
Home Design Overview
This custom-built Texas ranch-style home was designed with space, functionality, and long-term livability in mind. Rather than selecting a standard production floor plan, this Veteran worked directly with their builder to design a home tailored to their family's lifestyle — one of the clearest advantages of building with a VA construction loan over purchasing an existing resale property.
The layout prioritizes open-concept entertaining areas while maintaining clearly defined private retreats. Ceilings throughout are 10 to 12 feet, which is hard to find in comparable resale homes in this price range. Over 5,000 square feet of living space provide room for every need, with an additional 770 square feet of unfinished bonus space preserved for future expansion.
Main Living Area
The open-concept core connects kitchen, dining, and family room in one sweeping layout:
- Oversized kitchen with large central island
- Double ovens and walk-through pantry
- Open sightlines across the full living footprint
- 10–12 ft ceilings throughout
- Direct access to covered back patio
Primary Suite
Designed as a private retreat, separated from secondary bedrooms by the main living area:
- Generously sized bedroom footprint
- Large walk-in closets with built-in organization
- Spa-style bathroom configuration
- Split-bedroom layout for maximum privacy
Secondary Bedrooms
Three additional bedrooms in a dedicated wing — ideal for children, guests, or multigenerational living:
- Private wing separate from primary suite
- Private or shared bath access per room
- Full-size bedroom footprints throughout
Functional Spaces
Rooms Veterans often ask for, all included in this single VA construction loan build:
- Dedicated home office / study
- Large game room for family use
- Mudroom with built-in bench and storage
- Full laundry room with cabinetry
- Walk-through pantry
- ~770 sq ft unfinished bonus space
Exterior Design: A Timeless Texas Aesthetic
The exterior is classic Texas ranch architecture in durable materials. A brick and stone facade holds up well in North Texas weather and requires little maintenance.
Exterior highlights include multiple gables and varied rooflines for visual interest, an arched front entry, and a large covered back patio — an essential feature for outdoor living in Texas's climate. The three-car garage provides practical storage for an acreage property, where vehicle and equipment space is a priority for most Veteran families.
How the VA One-Time Close Construction Loan Worked on This Project
This home was financed using the VA One-Time Close Construction Loan. Here's how the loan worked from approval through permanent mortgage conversion on this North Texas project.
What the VA One-Time Close Construction Loan Allows Veterans to Do
The VA construction-to-permanent loan structure combined the land purchase, construction financing, and permanent mortgage into a single transaction. One application, one appraisal, one set of closing costs, one closing date. Here is specifically what that made possible on this project:
- Land and construction combined into one loan — the ~$150,000 land purchase and ~$650,000+ construction costs were rolled into a single $900,000+ VA loan. No separate land financing was required.
- No down payment required — eligible Veterans with full VA entitlement can finance 100% of total project costs, and this Veteran did exactly that.
- Interest rate locked at closing — before construction began, the Veteran's rate was secured. No exposure to rate increases during the 12-month construction period.
- No mortgage payments during construction — no monthly principal or interest payments while the home was under construction; the interest reserve and construction management fee were built into the loan amount and paid by the builder.
- Automatic conversion to permanent mortgage — when construction was complete and a certificate of occupancy issued, the loan converted to a standard VA mortgage. No second closing, no re-qualification.
Challenges & Lessons Learned on This VA Construction Loan Project
Every custom build — regardless of loan type — comes with complexity. The VA construction loan process adds documentation, coordination, and compliance requirements on top of the already involved custom home building process. Here is what came up on this project, so you can prepare for it.
- Builder Approval & Documentation Coordination Even with a builder experienced in acreage custom homes, the VA lender's builder approval packet required extensive documentation — including licensing verification, insurance certificates, financial references, and a review of comparable completed projects. This coordination required proactive follow-up and took longer than anticipated. Lesson: Begin builder approval conversations as early as possible — ideally before the loan application is submitted.
- Construction Draw Management Required Active Planning The draw schedule — the staged release of funds to the builder as construction milestones are completed and verified by a third-party inspector — required ongoing coordination between the builder, inspector, and lender. Delays in inspection scheduling or paperwork slowed draws and, consequently, construction momentum. Lesson: Establish clear communication protocols between your builder and VA construction loan lender before the first draw is requested.
- Design Upgrades Impacted the Overall Budget Mid-construction finish selections and minor structural modifications impacted costs beyond the original loan estimate. While the 2% contingency reserve built into this VA construction loan provided a buffer, significant changes required careful budget management. Lesson: Finalize all design selections as completely as possible before closing. Changes after the loan closes are more costly than decisions made upfront.
- Rural Site Work Extended Early Construction Timelines Acreage lots in North Texas often require more site preparation than suburban builds — including land clearing, grading, septic system installation, well drilling, and utility connections. These elements each require separate permitting and can push early construction timelines beyond initial projections. Lesson: Build a realistic buffer into your construction schedule estimate when working on rural Texas acreage.
Working with a VA construction loan lender who specializes in this product and has handled Texas acreage builds before makes these challenges easier to plan for. Construction loans need draw management and inspections that a standard VA purchase loan doesn't.
Who This Type of VA Construction Loan Build Is For
Not every Veteran needs a 5,300 sq ft custom ranch — but the financing structure behind this project applies to builds of every size and scope. If any of the following describes your situation, a VA One-Time Close Construction Loan may be the right path forward for your Texas build.
You Want to Build, Not Buy
The Texas resale market often means purchasing someone else's compromises — a layout that almost works, a location that almost fits, finishes that almost match your style. A VA construction loan lets you design and build exactly what you want, where you want it.
You Already Own Land (or Want to Buy It)
If you already own a land lot in Texas, it can typically be rolled into your VA construction loan — with your existing equity potentially reducing your VA funding fee. If you're purchasing land as part of the build, that cost is included in the single closing. No separate land loan required.
You Need a Custom Layout
Multi-generational living, a home office, workshop access, a game room, accessibility features — a custom build funded by a VA construction loan gives you control over every square foot that a production or resale home simply cannot provide.
You Want to Maximize Your VA Benefit
Many Veterans use their VA benefit once, for a standard purchase loan. The VA One-Time Close Construction Loan uses the same benefit to build: $0 down on loans up to $1 million, no PMI, a rate locked at closing, and a new custom home at the end of it.
Funding fee exemption: Veterans who receive VA disability compensation are exempt from the VA funding fee. On a $900,000 loan, the first-use fee with less than 5% down is 2.15%, or $19,350, so the exemption is a real savings. Non-exempt Veterans can finance the fee into the loan.
Start Your VA Construction Loan
If you're thinking about building a home like this in Texas, the first step is getting pre-approved and understanding exactly what your VA benefit can do for you. The VA One-Time Close Construction Loan process is more involved than a standard VA purchase loan — but with a lender that specializes in it, it is very doable for eligible Veterans across Texas.
Working with VA loan expert Shirley Mueller, you'll get direct guidance on pre-approval and your Certificate of Eligibility, realistic project cost and timeline expectations for your specific Texas location, help evaluating and connecting your chosen builder for lender approval, and hands-on management of the construction draw and inspection process throughout your build.